Area Real Estate News & Market Trends

You’ll find our blog to be a wealth of information, covering everything from local market statistics and home values to community happenings. That’s because we care about the community and want to help you find your place in it. Please reach out if you have any questions at all. We’d love to talk with you!

June 7, 2026

What are the best coffee shops in Huntington Beach

Score the perfect brew with these three highly-rated Huntington Beach coffee stops, offering everything from ethical single-origin roasts to beachfront breakfast bites and community-driven cafes.

Downtown (Fifth Street)

Sur Coffee This sleek craft roastery at 214 Fifth St brings globally sourced, farmer-direct beans to your cup. Swing by this downtown hot-spot for killer pour-overs, perfect espresso, and fresh pastries before hitting the sand.

They are a SoCal-based specialty roaster fueling your beach days with world-class coffee. For the last 10 years, they've scoured the globe for the finest single-origin beans, bringing them home to expertly roast and pour. Open 7 days a week, they are your ultimate pitstop before you hit the sand.


Downtown (Pier Area)

602 Coffee House

Overlooking the Pacific at 602 PCH, this isn't just a view-first cafe. Grab a signature Coastal Blend cold brew, a hearty açaí bowl, and a breakfast bite for the ultimate pre-beach walk fuel.

Where great coffee, fresh flavors, and coastal vibes collide. 602 is the ultimate coastal pick-me-up. Fuel up with their thick, loaded Açaí Bowls and hearty on-the-go sandwiches, all paired with the perfect cup of premium coffee. Catch the ultimate beach views and chill vibes at the Huntington Beach & Costa Mesa Locations.


Edinger

INC Coffee Roasters

Located on Edinger Ave, this welcoming neighborhood spot offers gourmet espresso, sandwiches, and retail beans. It pairs excellent coffee with a meaningful, inclusion-first mission that provides employment for people of all abilities.

In short, At i.n.c. (Inclusion), "We are redefining employment for people of all abilities. We adapt, we educate, and we hire. Our forever promise? Everyone is able, and there is a place for everyone to thrive."

Posted in Local News
June 5, 2026

How Do I Buy Real Estate If I Have No Social Security Number

1. The Cash Purchase Route

If you have the necessary funds, you can buy a property entirely in cash. You do not need an SSN, credit history, or legal residency status. You simply need a valid, government-issued photo identification (such as a foreign passport) to open an escrow account and record the deed. 

2. The ITIN Mortgage Route

If you need to finance the home, you can apply for an ITIN (Individual Taxpayer Identification Number) through the IRS. This is a tax-processing number available to non-citizens who are not eligible for an SSN. 


How to Qualify: Many credit unions and specialty portfolio lenders offer ITIN home loans. They will use your ITIN instead of an SSN to track your income and tax history.


Down Payment: Because these are not conventional government-backed loans (like Fannie Mae or Freddie Mac), lenders typically require a larger down payment, usually ranging from 15% to 20%. 


Credit History: If you do not have a U.S. credit score, lenders may accept alternative evidence of credit, such as consistent rent and utility payment history.

Because ITIN loan requirements and interest rates vary heavily by lender, shopping around is crucial. 

ITIN mortgage loans in California are specialized home loans designed for individuals without a Social Security Number who use an Individual Taxpayer Identification Number (ITIN) issued by the IRS.

Therefore, these loans have gained popularity among immigrant communities due to their accessibility and flexibility. Available statewide through select lenders, ITIN loans differ from traditional mortgages in documentation, interest rates, and eligibility requirements:

Jumbo loans require proof of income through tax returns and alternative credit history.

They usually have higher rates than conventional mortgages

Prioritize financial stability over credit scores for eligibility.


Unlike traditional loans, ITIN lenders assess credit using alternative methods like rent or utility payments. However, not all lenders offer ITIN products, making specialized lenders crucial for borrowers seeking this option.


Posted in Buying
June 4, 2026

How to Understand rental property economics

Rental property economics revolves around generating positive cash flow and building long-term equity through rent collection, market appreciation, and tax advantages. Success requires balancing rental income against operating costs and debt service to yield a healthy return on investment (ROI).


1. The Core Revenue & Cost Equation

Understanding whether an investment is profitable requires a clear breakdown of money coming in and going out.


Gross Income: Total rent collected, plus additional income like pet fees, parking, or laundry.


Operating Expenses: Day-to-day costs (typically 40% to 50% of gross income). These include property taxes, insurance, utilities, landscaping, and maintenance reserves (usually estimated at 1% of the property value annually).


Net Operating Income (NOI): Gross Income minus Operating Expenses.


Cash Flow: NOI minus your mortgage payments (Principal, Interest, Taxes, and Insurance - PITI).


2. Key Economic Metrics to Analyze a Deal

To evaluate if a property makes economic sense, investors rely on standard financial formulas.


Cap Rate (Capitalization Rate): Calculates the return on a property assuming it is bought in all cash.\(Cap \, Rate = \frac{Net \, Operating \, Income}{Purchase \, Price}\)


Cash-on-Cash Return (CoC): Measures the actual return on the cash you invested out of pocket, which is heavily impacted by leverage (mortgages).\(CoC \, Return = \frac{Annual \, Cash \, Flow}{Total \, Cash \, Invested}\)


Rent-to-Value (RTV) Ratio: Used to evaluate a market's viability. Many investors target properties where the monthly rent is 0.8% to 1% of the purchase price.\(RTV \, Ratio = \frac{Monthly \, Rent}{Purchase \, Price}\)


3. Drivers of Profitability

The economic health of a rental property is influenced by several external and internal factors.


Vacancy & Turnover Rates: Every day a property sits empty represents lost income. Investors typically subtract 5% to 8% of projected income for vacancies and turnover costs.Leverage: Using a mortgage increases your purchasing power but adds a debt burden that lowers immediate cash flow.


Property Management: Outsourcing management to professionals typically costs 8% to 12% of gross rents, which cuts into profit margins but saves time.

4. Long-Term Value (The 3 Pillars of Returns)

Real estate generates wealth through three economic engines.


Cash Flow: The immediate, spendable income distributed after all bills are paid.


Appreciation: The natural increase in the property's market value over time, bolstered by inflation and area development.


Tax Benefits: Landlords can deduct expenses such as mortgage interest, insurance, and maintenance, in addition to claiming depreciation (deducting a percentage of the property's cost each year) to significantly lower taxable rental income.For a deeper dive, you can explore detailed deal breakdowns on Investopedia's Ultimate Guide to Investing.

Posted in Buying
June 1, 2026

Orange County Luxury Market Update

The luxury market in Orange County slowed over the past couple of weeks.

In the past couple of weeks, the luxury home inventory priced above $2.5 million (the top 10% of the Orange County housing market) increased from 987 to 1,041, up 54 units, or 5%. Luxury demand decreased by 12 pending sales, down 6%, to 199. With supply rising and demand falling, the Expected Market Time for luxury homes priced above $2 million increased from 149 to 167 days, its slowest reading since January. Like the rest of the market, the luxury market is beginning to slow.

Year over year, the active luxury inventory is down by 177 homes (-15%), and luxury demand is down by 1 pending sale (-1%). Last year’s Expected Market Time was 194 days, slower than today.

In the past two weeks, the Expected Market Time for homes priced between $2.5 million and $4 million increased from 115 to 128 days. For homes priced between $4 million and $6 million, the Expected Market Time increased from 142 to 177 days. For homes priced above $6 million, the Expected Market Time increased from 281 to 295 days. Luxury is at 167 days overall. At this pace, a seller would likely become a pending sale around November 2026.

May 31, 2026

What are the pros and cons of selling a house yourself?

For-Sale-By-Owner (FSBO) transactions carry significant financial and legal perils. Sellers often face reduced sale prices, liability for disclosure failures, and complex contract errors. Navigating negotiations unrepresented also leaves sellers highly vulnerable to legal disputes and scams. Understanding the primary hazards is essential for anyone considering a real estate transaction without professional representation.


1. Pricing Pitfalls

Overpricing: Emotional attachment or relying on unverified estimates can lead sellers to list above market value. This causes homes to sit on the market longer, requiring price cuts that signal red flags to buyers.


Undervaluing: A lack of access to local, real-time Multiple Listing Service (MLS) data can cause sellers to price too low, leaving thousands of dollars on the table


2. Legal and Disclosure Risks

Disclosure Failures: Sellers are legally obligated to disclose any known material defects. Failing to do so—even accidentally—frequently results in costly post-closing lawsuits for fraud or misrepresentation.


Contract Errors: Real estate contracts are binding legal documents. Missed deadlines, vague clauses, or improper contingencies can lead to delayed closings, legal disputes, or the total collapse of the sale.


Fair Housing Violations: FSBO sellers must comply with strict state and federal housing laws. Ignorance of discriminatory advertising or showing rules does not protect sellers from penalties.


3. Limited Exposure and Buyer Pool

Missing Out on Agents: Real estate professionals rely on extensive networks. Because buyers' agents earn commissions, they might be hesitant to show their clients FSBO homes—either out of concern that the seller won't pay the commission or because the seller may be difficult to work with.

Reduced Visibility: Listing on the MLS, which is the most reliable way to get a home in front of active buyers, often requires paying a flat fee to a broker or using specialized listing services.

4. Vexing Negotiations and Scams

Emotional Clashes: Real estate negotiations can be tense. Without an objective agent to buffer communications, direct negotiations between buyers and sellers can easily derail deals over minor repairs or concessions.


Scams and Security: FSBO transactions often attract predatory buyers or scammers. Sellers must be wary of false purchases, fraudulent earnest money deposits, and identity theft when handing over sensitive property information


5. Closing Complications

Escrow and Title Issues: Navigating title searches, clearing property liens, and managing escrow accounts requires technical expertise. Mistakes made during the closing phase can prevent the transfer of ownership or cost the seller money.

Posted in Selling
May 29, 2026

What to do with pets during showings?

Selling your home is a whirlwind, and staging it with a menagerie underfoot can be a nightmare. The best strategy is to relocate your pets completely—ideally to a local doggy daycare, a trusted friend's house, or a pet-friendly boarding facility—to keep your furry best friends safe and potential buyers completely focused on your home. Here is a quick, stress-free playbook for managing your pets during house showings:


1. Make a Temporary Relocation Plan 

The Daycare Option: Drop your pets at a trusted local doggy daycare or boarding facility. It burns off their energy so they are relaxed and happy when they return.  

The Playdate Pivot: Ask a local friend, family member, or trusted neighbor to host your pet for a few hours.

The Purr-fect Day Trip: If you have an outdoor space, consider a Pet-Friendly Hotel or cat hotel for the day so your pet gets a vacation too!


2. If They Must Stay on Property

If you can't transport them away from home during a showing, you need a safe on-site strategy:

The Traveling Crate: Place your pets in secure, comfortable crates in an out-of-the-way area, like the basement or a large walk-in closet. Always leave a polite note for agents to avoid opening these doors.

The Backyard Retreat: Weather permitting, let outdoor-loving pets hang out in a clean, secure backyard or kennel.

The "Do Not Enter" Room: Designate one specific bedroom or room as a safe haven. Add a highly visible sign on the door (e.g., “Pet inside! Do not enter, please keep door closed”) so agents and buyers know to steer clear.


3. The Pre-Showing Purge (For You, Not Them!)

No matter where they are, your home needs to smell and look completely pet-free to appeal to buyers:

Hide the Gear: Stow away food bowls, litter boxes, toys, and crates in a sealed plastic bin. Hide it all in the garage or your car.

The Odor Offense: Vacuum thoroughly, wash pet beds, and use neutral odor eliminators.

Spotless Check: Double-check carpets and furniture for any stray hair. If you use a Petcube Camera to monitor your pets, quickly stash your phone away so buyers don't feel like they are being watched. By taking these proactive steps, your home stays spotless, buyers can easily envision their own lives in the space, and your pets stay safe and stress-free!

Posted in Selling
May 27, 2026

What is an ADU?

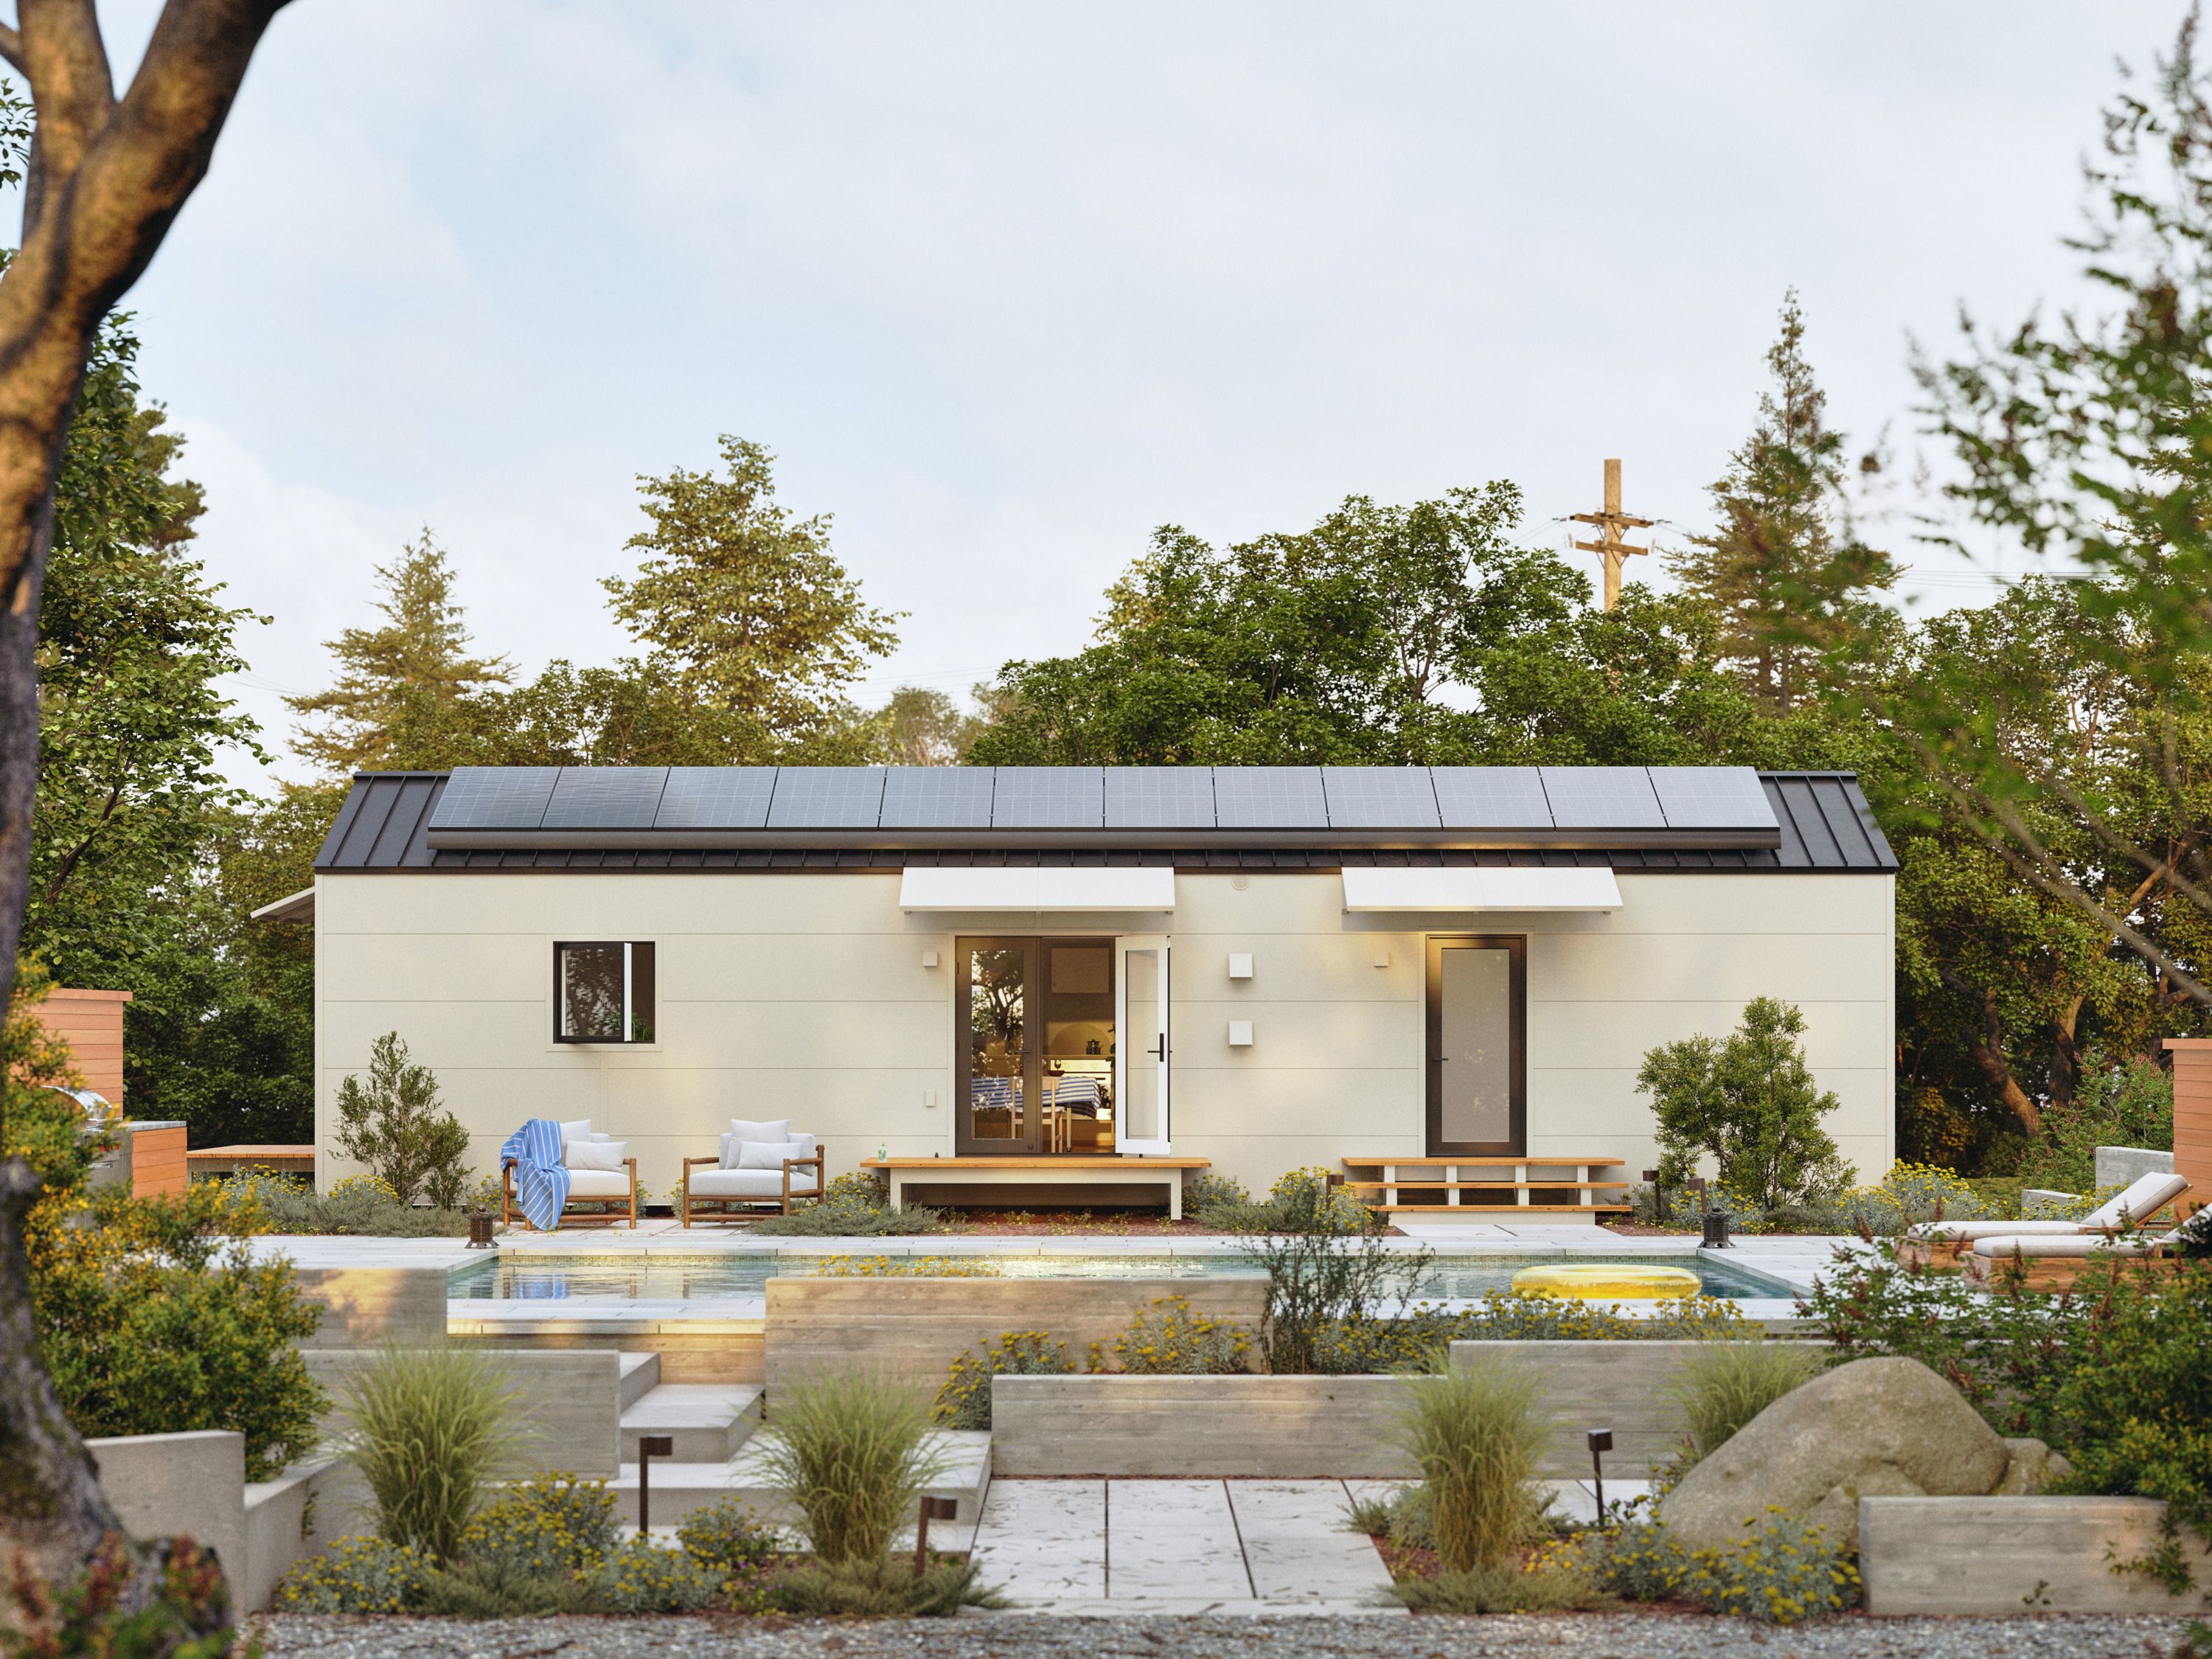
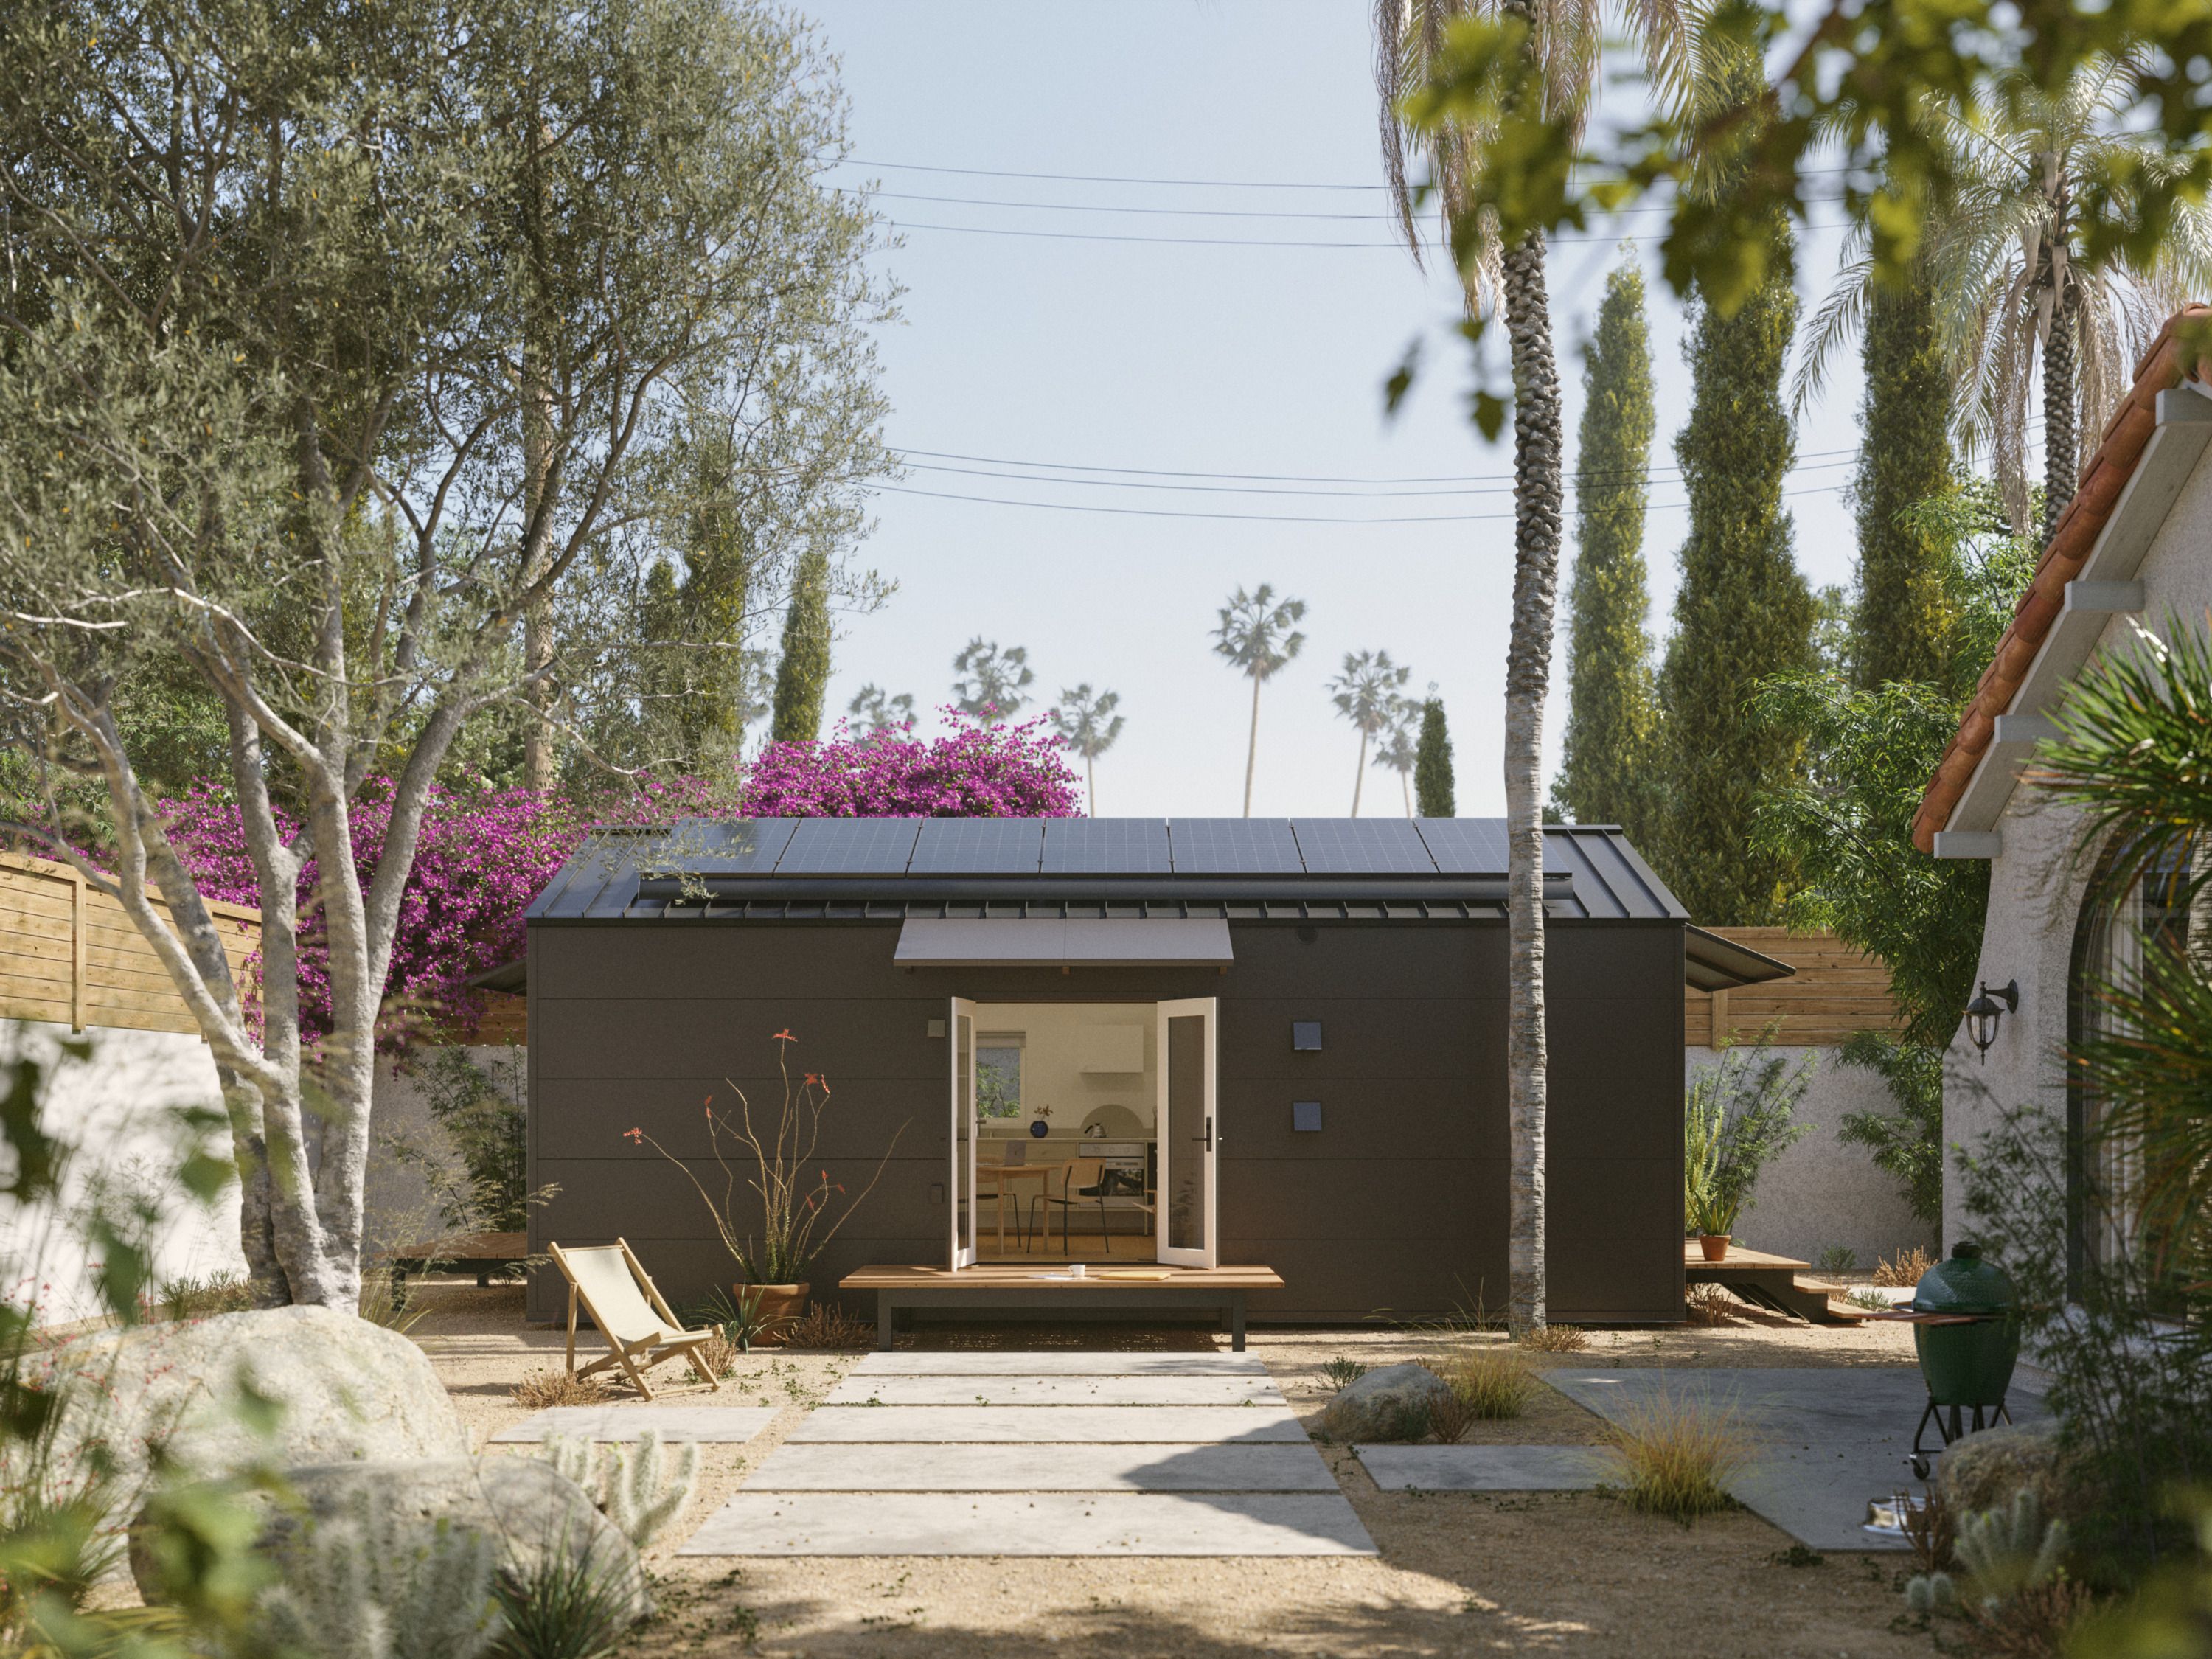
Accessory Dwelling Units (aka ADUs, granny flats, or backyard cottages) are having a major moment. Whether you want to boost your property value, score some passive rental income, or finally give your mother-in-law her own space, these tiny homes deliver massive benefits. But what exactly counts as an ADU—and is your backyard ready for one? Let’s break it down.

Independent Living Space: An ADU functions as a separate residence with its own kitchen, bathroom, and private entrance.

Secondary to a Primary Dwelling: It cannot stand alone and must share the same lot as the main home.

Compact Size: While sizes vary, most cities have a cap on square footage, typically 500 to 1,200 square feet.


1. Detached ADUs (The DADU)

Think backyard cottages, casitas, or standalone tiny homes. It's your own private island... just steps from the back porch.


The Good: Ultimate privacy and total design freedom.


The Bad: It’s a ground-up build, meaning a bigger hit to your wallet for foundations and utilities.


🔌 2. Attached ADUs

This is an addition or a new wing physically connected to your main house.


The Good: Shared walls mean shared infrastructure—saving you some serious construction cash.


The Bad: You’ll probably hear your tenant (or your teenager) through the wall. Privacy is a bit compromised.


🚗 3. Garage Conversions

The ultimate recycling project. You take your existing garage and flip it into a chic livable space.


The Good: The bones are already there! It’s fast, efficient, and budget-friendly.


The Bad: Say goodbye to covered parking, and hello to a strict square-footage limit.


🪵 4. Interior ADUs (Basements & Attics)

Carving out an apartment entirely within your current home’s footprint.


The Good: Super cost-effective since you aren't adding to the house. Plus, it makes great use of forgotten space.


The Bad: Heavy remodeling ahead. You might need to raise ceilings, add separate entrances, and figure out soundproofing.


1. The Ultimate Side Hustle

Rent it out to long-term tenants or weekend travelers. It's a steady stream of passive income that can help destroy your mortgage.

📈 2. Serious Property Flex

Adding a chic mini-home to your lot instantly boosts your home’s resale value and catches the eye of future buyers.

🔑 3. Proximity + Privacy

Keep your adult kids or aging parents close by. An ADU gives everyone the independence they want with the support they need.

🌆 4. Fighting the Housing Crunch

ADUs provide much-needed, affordable housing options in crowded cities without ruining the neighborhood vibe.

🌱 5. Tiny Footprint, Big Savings

Smaller spaces require way less energy to heat and cool. It’s an easy win for your carbon footprint and your monthly utility bills.

May 26, 2026

What is premium living?

Premium living refers to homes and developments that offer an elevated, lifestyle-driven experience. Rather than just pure status or prestige, it emphasizes exceptional build quality, top-tier amenities, smart-home technology, and a highly desirable location—all designed to maximize comfort and convenience.


The concept of a premium property generally breaks down into these key pillars:


Prime Location: Properties are situated in highly sought-after areas, offering great walkability, scenic views, or close proximity to upscale dining, shopping, and business hubs.

Living close to major commercial centers ensures that professionals spend less time commuting and more time enjoying life. A home near a business district also attracts high demand, making it a sought-after asset for resale or rental income.

Premium living extends beyond the four walls of a home. The presence of reputed schools, multi-specialty hospitals, fine-dining restaurants, and high-end shopping centers within a short radius adds immense value. Access to world-class facilities ensures that residents experience convenience at every step.


A premium property should provide seamless access to major highways, expressways, metro stations, and airports. Quick connectivity reduces travel stress and enhances accessibility, whether for daily commutes or international travel. Well-planned infrastructure surrounding a property significantly impacts its long-term desirability and price appreciation.


Superior Construction & Design: Homes feature high-end materials (e.g., imported marble, custom cabinetry) and architectural distinction. They prioritize energy efficiency, sustainability, and soundproofing.


A premium home is defined by superior build quality and thoughtful design. High-end properties use top-tier materials like Italian marble, hardwood flooring, and imported fittings, ensuring durability and elegance.


The choice of materials speaks volumes about a home’s luxury quotient. Italian marble flooring, premium hardwood, designer wall finishes, and imported bathroom fittings elevate the interiors. These materials ensure durability, aesthetic appeal, and a touch of sophistication, setting the home apart from standard constructions.

Beyond aesthetics, structural integrity is key. Earthquake-resistant frameworks, fireproofing, and high-grade materials enhance safety and longevity. Spacious, well-lit interiors with large windows, high ceilings, and optimal ventilation create an airy, comfortable living space.


Lastly, timeless architecture blends luxury with functionality. Grand facades, intricate detailing, and modern layouts ensure lasting appeal. A truly premium home is not just about looks—it is about quality, security, and enduring value.


Luxury is not just about size but also about how space is utilized. Premium homes boast open floor plans, expansive balconies, high ceilings, and large windows that allow ample natural light. Thoughtful ventilation enhances air circulation, creating a bright and refreshing living environment. Smart space utilization ensures that every corner of the house adds to comfort and aesthetics.
Lifestyle-Driven Amenities: Premium developments often function as self-sufficient ecosystems, providing exclusive access to private gyms, pools, spas, concierge services, and landscaped communal spaces.


Enhanced Privacy & Security is vital in premium living: These properties prioritize exclusivity through gated entries, 24/7 biometric and CCTV surveillance, low-density layouts, and quiet environments.


A premium home offers not just luxury but also unmatched security and privacy. High-end residences feature 24/7 CCTV surveillance, biometric access, and gated communities with trained security personnel. These measures ensure a safe living environment for residents.


Privacy is equally vital, with low-density layouts, soundproof walls, and exclusive access lifts preventing disturbances. Thoughtful landscaping further enhances seclusion.


Additionally, smart home security systems allow homeowners to monitor and control access remotely. A premium property prioritizes safety and exclusivity, offering residents complete peace of mind.
Posted in Buying, Selling
May 25, 2026

What are luxury home design trends

The global shift toward minimalist luxury—often dubbed "quiet luxury"—redefines prestige by prioritizing refined simplicity, intentionality, and craftsmanship over overt opulence. Driven by evolving consumer values, it replaces visual clutter with architectural discipline and high-end materials to create a serene sanctuary.


The Core Drivers

Digital Fatigue: In an era of constant digital stimulation and social media noise, uncluttered spaces provide crucial visual rest and mental clarity.

Conscious Consumption: Modern consumers tie sustainability to status. Restraint and quality over quantity communicate progressive, responsible values rather than excess. 

The "If You Know, You Know" Effect: Rather than broadcasting wealth through loud logos or ornate decoration, prestige is communicated through impeccably tailored silhouettes, hidden smart technology, and flawless execution.


Defining Characteristics 

Material Authenticity: Minimalist luxury relies on a deeply reduced, neutral color palette, which requires exceptional, high-quality materials to provide depth. Expect to see exposed concrete, premium metals, solid wood, and natural stone.


Sensory Architecture: Design emphasizes how a space feels rather than how it looks. This includes bringing in abundant natural light, blurring boundaries between indoors and outdoors, and prioritizing acoustic comfort.


Invisible Technology: Smart home systems are highly integrated but entirely out of sight, ensuring that clean surfaces and uncluttered lines remain the focal point.


Broader Implications

Experts observe that this "less is more" philosophy extends far beyond physical spaces and into fashion, travel, and consumer goods. Exploring platforms like [Nolita Harbour] (-minimalist- interiors-became-the-new-language-of-luxury-living/) outlines how interior design reflects this global sophistication, while analyses on Plastic Free Pursuit detail why the definition of luxury has transformed from "owning more" to "feeling better."

Posted in Buying, Selling
May 25, 2026

How Much are Closing Costs?


Expect 2-5% of the purchase price for fees, title insurance, appraisal, etc.  

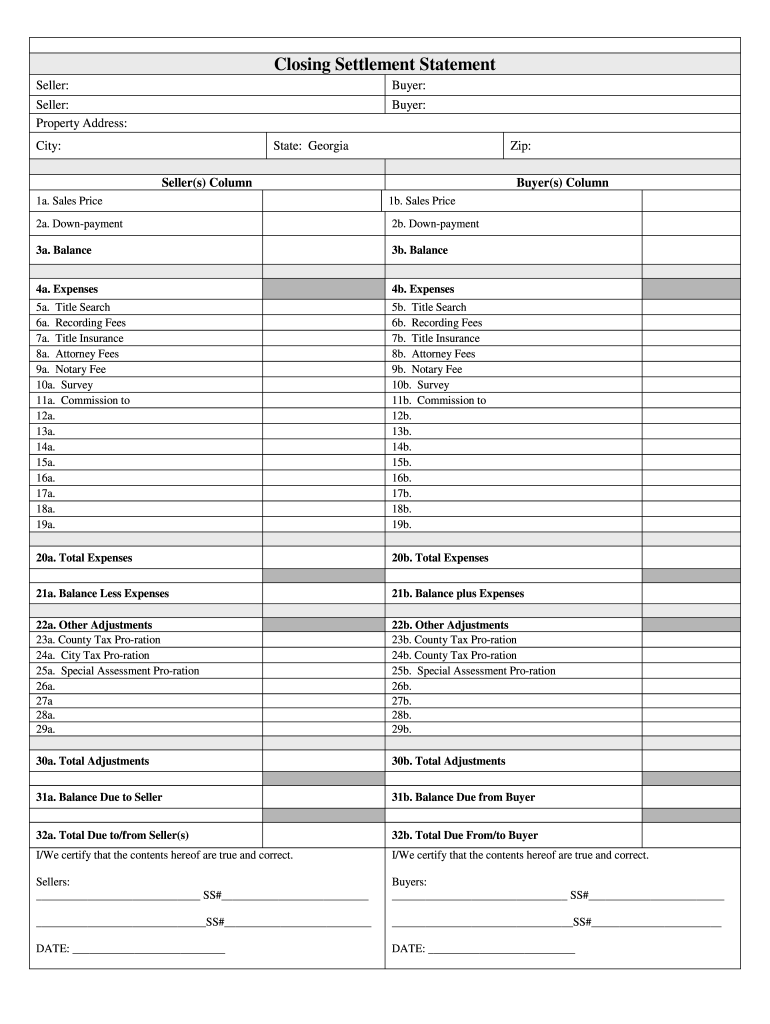
A closing statement (or settlement statement) summarizes all financial transactions of a home sale. It outlines the final purchase price, prorated property taxes, agent commissions, and loan payoffs. The bottom line reveals your exact net proceeds as the seller or the total cash needed to close as the buyer.

The summary is generally split into debits (costs/amounts owed) and credits (funds received/refunds). A standard closing statement summary for a home sale typically includes the following breakdowns:


Financial Summary 

Contract Sales Price: The total agreed-upon purchase price of the home.

Earnest Money Deposit: The initial good-faith deposit paid by the buyer, which is credited toward their purchase.


Seller Deductions (Costs)

Mortgage Payoff: The outstanding principal balance on your current mortgage.

Broker Commissions: The agreed-upon percentage (usually 5% - 6%) paid to the real estate agents.

Title & Escrow Fees: Costs for title insurance, settlement/closing fees, and notary services.

Transfer Taxes & Recording Fees: Government fees required to officially record the new deed and transfer ownership.

Prorated Property Taxes & HOA Dues: Any property taxes or homeowner association fees you owe for the days you owned the home during the closing month, which will be credited to the buyer.


The Bottom Line Due from Borrower: The final out-of-pocket cash the buyer must bring to closing (down payment + closing costs - earnest money).


Cash to Seller: The final net proceeds the seller will receive from the sale after all deductions and prorations have been settled.

To explore a detailed breakdown of a settlement statement, refer to the Consumer Financial Protection Bureau Sample Closing Disclosure for buyers, or use a general Title Company ALTA 


CREDITS. 

1. Purchase Price. 

2. Deposit (Earnest Money) Paid to: 

3. Principal amount of new 1st Loan Payable to: 

4. Princip...California DRE (.gov)


SETTLEMENT STATEMENT - Coast Cities Escrow

GROSS AMOUNT DUE FROM BORROWER: 400. 


GROSS AMOUNT DUE TO SELLER: 101. Contract Sales Price 401. Contract Sales Price 102. Personal...Coast Cities Escrow 


Updated May 25, 2026


Posted in Buying, Selling