Area Real Estate News & Market Trends

You’ll find our blog to be a wealth of information, covering everything from local market statistics and home values to community happenings. That’s because we care about the community and want to help you find your place in it. Please reach out if you have any questions at all. We’d love to talk with you!

May 24, 2026

How Luxury Properties Differ from Standard Homes

How Luxury Properties Differ from Standard Homes

Luxury properties stand out from standard homes in design, materials, amenities, location, and price, reflecting a focus on exclusivity, comfort, and investment potential.


1. Location and Setting

Luxury homes are often in prime, exclusive neighborhoods—coastal areas, city penthouses, gated estates, or remote private lands—offering privacy, scenic views, and easy access to premium amenities like private clubs, restaurants, and parks wearemonest.com+1. Standard homes are typically in mid-range or suburban areas with basic community facilities.


2. Design and Craftsmanship

Luxury properties feature custom architectural designs, high-end finishes, and meticulous craftsmanship. They use premium materials like marble, granite, hardwood, and designer fixtures, with attention to detail in every room Bromundlaw+1. Standard homes use common materials and finishes, with simpler, more uniform designs.


3. Size, Space, and Layout

Luxury homes often have larger floor plans with multiple living areas, high ceilings, and expansive outdoor spaces such as pools, gardens, and terraces. Standard homes focus on functional layouts that meet basic needs without excess space.


4. Amenities and Features

Luxury homes include specialized, high-end amenities such as wine cellars, home theaters, private gyms, spa bathrooms, smart home technology, gourmet kitchens, and finished garages.  Standard homes have basic appliances and fixtures, with limited customization.


5. Price and Investment Value

Luxury properties typically start above $1 million and can be much higher, reflecting their exclusivity and premium features.  Standard homes are priced in the $300,000–$700,000 range for most markets. Luxury homes often offer higher appreciation potential in desirable markets www.luxeglobalre.com.


6. Lifestyle and Exclusivity

Luxury homes cater to affluent lifestyles with privacy, security (e.g., 24/7 surveillance, gated communities), and unique personalization options www.luxeglobalre.com. Standard homes prioritize affordability and practicality.


In summary:

Luxury properties are defined by exclusive locations, custom design, premium materials, expansive and specialized amenities, and high prices, while standard homes focus on affordability, functionality, and basic comfort. The choice often depends on lifestyle, budget, and investment goals.

Posted in Buying, Selling
May 11, 2026

Huntington Beach Current Market Stats

Huntington Beach Stats as of May 11, 2026: current active listings are 298.  The market time is 64 days.  The market time was 73 days one year ago.  The current median price is $1.4M


Updated May 2026

May 8, 2026

How to improve your home's backyard value?

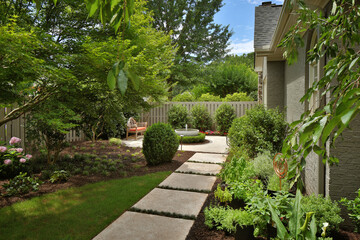
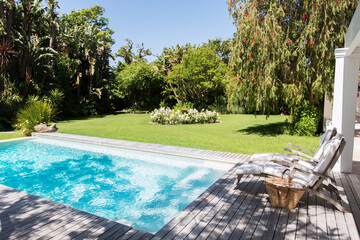
A well-designed backyard can increase your home's value by up to 15-20%. In 2026, outdoor living spaces have become the most desired feature for homebuyers, often outranking interior upgrades because they expand usable living area without the cost of a full home addition.

Decks & Patios: These features create "outdoor rooms" for dining and relaxing. A new wood deck typically recoups about 83% of its cost, while patios see an average ROI of 60% to 70%.

Outdoor Kitchens: Increasingly popular as "culinary suites," functional outdoor kitchens with built-in grills and durable countertops can recoup 55% to 200% of their cost, depending on the market.

Mature Trees: A healthy, mature tree can increase property value by $1,000 to $10,000 by providing shade, privacy, and aesthetic appeal.

Fire Features: Permanent fire pits or outdoor fireplaces serve as natural gathering spots and can offer a 50-70% ROI. 


Key Value Drivers for 2026

Expanded Living Space: Buyers perceive decks, patios, and pergolas as "bonus square footage" for hosting and relaxing.

Privacy: Enclosed yards with high-quality fencing (wood or vinyl) or "green screens" like hedges are top priorities for buyers with children or pets.

Sustainability: Eco-friendly features like native, drought-resistant plants (xeriscaping), solar-powered lighting, and smart irrigation systems are highly attractive to modern, eco-conscious buyers and lower future maintenance costs.

Nighttime Ambiance: Professional outdoor lighting enhances safety and expands the yard's usability after dark, adding roughly $2,500 in perceived value


Features to Avoid

Certain upgrades may actually detract from value or fail to recoup costs: 

Over-Personalization: Highly specific features like built-in trampolines, elaborate themed gardens, or specialized sports courts can limit buyer interest.

High-Maintenance Items: While pools can be a major selling point in warmer climates, they may only recoup about 56% of costs due to perceived maintenance burdens.

Excessive Concrete: Large, plain concrete slabs can create "heat islands" and drainage issues, potentially lowering value by up to 12% compared to yards that mix hardscaping with greenery

Posted in Selling
May 2, 2026

How to identify high-potential investment properties

Spotting a high-potential property requires a comprehensive analysis of factors such as location and neighborhood quality, market trends, and financial metrics. By carefully evaluating these indicators, you can identify properties that promise strong returns and long-term value.


Location, Location, Location

The importance of location cannot be overstated in real estate investment. Properties in prime locations tend to appreciate faster and attract high-quality tenants. Consider the following aspects of a property's location:

Proximity to Amenities: Properties near schools, parks, shopping centers, public transport, and healthcare facilities are highly desirable.

Employment Opportunities: Areas with growing job markets attract more residents, increasing demand for rental properties.

Future Developments: Planned infrastructure projects, such as new roads, public transport, and commercial developments, can significantly boost property values.


Neighborhood Quality

The quality of the neighborhood plays a crucial role in the property's long-term viability and rental appeal. Look for:

Safety: Low crime rates and security are top priorities for tenants and buyers.

Community Vibes: Friendly, well-maintained neighborhoods with a strong sense of community are more attractive.

School Districts: Properties in reputable school districts tend to have higher demand and can command premium rents.


Property Condition and Features

The property's condition and features directly impact its value and rental potential. Key considerations include:

Structural Integrity: Ensure the property is structurally sound with no major issues like foundation cracks or roof leaks.

Modern Amenities: Features like updated kitchens and bathrooms, energy-efficient appliances, and smart home technology can add value.

Curb Appeal: A well-maintained exterior with attractive landscaping can increase the property's desirability.


Market Trends and Comparables

Understanding current market trends and analyzing comparable properties (comps) can help you gauge a property's potential.

Historical Data: Examine historical appreciation rates for properties in the area to assess future value growth.

Rental Rates: Compare rental rates of similar properties to estimate potential rental income.

Days on Market: Properties that sell or rent quickly indicate strong demand in the area.

Economic Indicators

Broader economic factors can also influence a property's investment potential. Consider:

Interest Rates: Lower interest rates make borrowing more affordable, boosting property demand.

Economic Growth: A robust local economy with diverse industries can support steady property appreciation.

Population Growth: Areas with increasing populations generally see rising property values and rental demand.


Development Potential

Some properties offer additional value through development potential:

Zoning Laws: Check if the property is in an area where zoning laws allow for future development or modifications.

Land Size: Larger plots of land may offer opportunities for expansion or subdivision.

Renovation Potential: Properties in need of renovation can be bought at a lower price and improved for higher resale or rental value.


Financial Metrics

Evaluating key financial metrics is essential to determine the property's profitability:

Cap Rate: The capitalization rate (net operating income divided by purchase price) helps you understand the expected return on investment.

Cash Flow: Ensure the property generates positive cash flow after accounting for mortgage payments, taxes, insurance, and maintenance costs.

ROI: Calculate the return on investment by comparing the property's net income to the initial investment cost.


Conclusion

Spotting a high-potential property requires a comprehensive analysis of factors, including location and neighborhood quality, market trends, and financial metrics. By carefully evaluating these indicators, you can identify properties that promise strong returns and long-term value.

Identifying high-potential investment properties in 2026 requires a rigorous, data-driven approach that balances current cash flow with long-term appreciation. As the market stabilizes, focusing on areas with strong job growth, improving affordability, and specialized property types will yield the best results.

Here is a comprehensive framework for identifying, analyzing, and selecting investment properties that promise strong returns.


1. The 2026 Location Strategy: Beyond the City Center. Prime location no longer exclusively means dense urban cores. Emerging markets with strong employment and lower living costs often offer better returns. Job Growth & Economic Diversity: Target cities experiencing population influx, especially tech hubs, and regions attracting new businesses (e.g., Irvine, Stanton, Anaheim markets).

"Last-Mile" and Suburb Proximity: Properties close to major suburban employment centers, transit, and medical districts are highly sought after by renters seeking flexibility.

Future Infrastructure Improvements: Analyze city planning reports for new roads, transit lines, or commercial hubs. Areas with upcoming infrastructure investments generally experience higher appreciation.


2. Neighborhood Quality and Viability A neighborhood's trajectory matters more than its current state.

Safety Metrics: Check police data but focus on the trend—improving safety indicates potential for rising property values. School Districts: High-rated schools remain a consistent driver of value and attract long-term, family tenants.

Local Vibes & "Sticky" Features: Look for walkable areas with amenities like coffee shops, parks, and grocery stores. These amenities attract millennials and families, increasing demand.


3. Property Condition and Value-Add Potential. While turnkey properties offer ease, "value-add" opportunities—properties requiring cosmetic updates—often yield the highest ROI.

Structural Soundness: Prioritize structural integrity over cosmetic beauty; a solid foundation, roof, and plumbing are paramount.

Modernization Opportunities: Look for properties with outdated layouts or finishes (e.g., kitchens, bathrooms) that can be renovated to increase rental income. Sustainability & Technology: As of 2026, energy-efficient features, smart home technology, and low-maintenance materials (like LVP flooring) are key differentiators that reduce turnover costs and attract higher-quality tenants.


4. Market Trends, Metrics, and Comparables

Before making an offer, you must validate the potential returns using specific financial metrics. 

Cap Rate (Capitalization Rate): A higher cap rate generally signals a better return relative to the property's cost.Cash 

Flow & ROI: Calculate net income after all expenses. A healthy rent-to-price ratio (often seeking 1% or higher) is crucial for positive cash flow.

Comparable Sales (Comps): Analyze 12-24 months of sales data to ensure your purchase price aligns with current market demand.


5. High-Potential Property Types in 2026 Single-Family Residential homes (SFR's): Remain the safest investment, particularly in high-growth suburban communities.

Build-to-Rent (BTR): Specialized communities of single-family homes or townhomes designed specifically for renting are in high demand.

Multifamily: Smaller multi-unit properties (2-4 units) allow for "house hacking," enabling investors to live in one unit while renting the others.

Summary Check: High-potential properties in 2026 are often located in growing, secondary markets, feature modern, energy-efficient amenities, and are validated by strong rental-to-price ratios.

Posted in Buying
May 2, 2026

What Are Home Decorating Tips to Inspire Buyers?


What Are Home Decorating Tips to Inspire Buyers?

  • Kill the Clutter, Not the Charm: Pack away personal photos and knick-knacks. Let buyers visualize their life, not yours.
  • Stage for the Masses: Neutralize colors and style for the target buyer, not your own taste.
  • Flaunt Your Features: Highlight architecture (fireplaces, moldings) with simple, strategic furniture placement.
  • Paint it Pretty & Uniform: Paint baseboards the same color as walls for a seamless, sky-high ceiling effect.
  • Let the Sunshine In: Ditch heavy drapes, wash windows, and use mirrors to bounce light everywhere. 
  • Create a "Pause Point": Style your entryway with a mirror, small table, or rug to make a great first impression.
  • Layer Texture, Not Color: Keep colors neutral, but add depth with leather, linen, and wood accents.
  • Mirror, Mirror on the Wall: Strategically place mirrors to make tight spaces feel twice as big.
  • Choose a "Hero" Piece: One bold piece of art or a chic light fixture can anchor a room and add instant luxury.
  • Keep it Functional: Ensure the layout makes sense—showcase flow and usability in every room. 
Posted in Selling
April 27, 2026

What is curb appeal and how to enhance it?

What is curb appeal and how to enhance it?

Curb appeal—the initial attractiveness of a home’s exterior from the street—is vital for selling, as it creates a crucial first impression, influences buyer trust, and can speed up the sale process. Strong curb appeal enhances market value, often allowing for higher offers and faster sales, as buyers often equate a well-maintained exterior with a well-maintained interior. Enhancing it involves creating an inviting, clean, and well-lit entry with manicured landscaping.


What is the importance of Curb Appeal?

Crucial First Impression: Buyers often decide within seconds if they are interested, making the exterior (including online photos) the first, and sometimes final, impression.

Perceived Value and Price: A "wow factor" exterior can increase a home’s value by up to 10% and justifies a higher asking price.

Higher Offers & Faster Sales: Appealing homes attract more buyers, reducing time on the market.

Builds Trust: A tidy exterior suggests that the seller has maintained the entire property, reducing fears of hidden, costly repairs.


How to Enhance Curb Appeal When Selling 

Landscaping & Lawn Care: Mow the lawn, trim shrubs, weed flower beds, and lay fresh mulch to make the yard look pristine. 

Elevate the Entrance: Repaint the front door (perhaps a vibrant, welcoming color), replace old house numbers, and hang a new, modern mailbox. 

Clean and Clear Clutter: Power wash siding, walkways, and driveways. Remove toys, trash, and personal items from the yard and porch. 


Add Strategic Lighting: Install solar lighting along walkways, and add new, modern light fixtures on the front porch to make it look safe and inviting in the evenings. 

Stage the Front Porch: Place potted plants, a new doormat, and outdoor furniture (like a chair or small bench) to create a welcoming, lived-in feel. Install Window Boxes


Posted in Selling
April 24, 2026

What Are The Safest Huntington Beach Area Neighborhoods


Safest Huntington Beach Area Neighborhoods

Huntington Beach Crime Rates and Statistics - NeighborhoodScout

1. Seacliff area south of Garfield bounded by Goldenwest, Seapoint and PCH

2. Davenport Island in Huntington Harbour

3. Bolsa Chica Bounded by Edinger, Bolsa Chica, Graham and Warner

4. Huntington Place in South Huntington Beach area

5. Lagenbeck Park near Garfield and Newland

6. Meredith Gardens near Brookhurst and Garfield

7. Villa Pacific/Huntington Showcase near Brookhurst and Hamilton

8. Pacific Sands/Beachside

9. Edwards Hill/Oceanview Estates 

10. Deane Gardens in South HB southwest of Brookhurst Street, northeast of Park Place/Seabury with boundaries of Brookhurst, Hamilton, Magnolia and PCH 


See the current crime in Huntington Beach


Posted in Buying
April 22, 2026

What are Questions to Ask a Loan Officer or Mortgage Broker

Whether you are working with a loan officer or mortgage broker, it is essential to ask questions.

Before looking at homes, it’s wise to get your selection of a lender squared away first. Preparing to get a loan is asking your mortgage lender the right questions.


When you first start looking for a lender to help you buy a home, it is normal to feel like it’s a one-way street—you need the money, so anyone who will offer it to you seems like someone you should do your best to listen to.


When buying your first house, many things can seem foreign to you.


But in reality, you are an essential customer for your lender. Your business is critical to the company.


It’s how they make their money and how they stay in business. So it is worth stepping back for a moment to orient yourself correctly.


As with any business deal, you must look for your best interests and act confidently. Understanding how to choose a lender is critical in shopping for a home.


The terms and conditions you get on your mortgage will be crucial in your financial picture for years to come.


It makes sense to do your best to vet the mortgage lender, the interest rate, and other loan terms.


1. What Documents Will I Need to Get a Loan?

One of the most important questions you will ask your loan officer or mortgage broker is what documents they need. If the mortgage officer is worth their salt, they’ll tell you before you even ask.


The mortgage documents required to grant a home loan will vary depending on your chosen program.


Depending on the loan program you end up you’ll more than likely need these things to grant a mortgage

Identification – either a driver’s license, passport, or official state/federal ID.

Income – including 30 days of pay stubs, your previous two years of federal tax returns, your last two W-2s, and proof of any additional income.

Accounts include bank statements for the last two cycles and investment or retirement accounts.

Property – a statement showing the settlement of your prior home if you had one.

Additional documents – forms such as a gift letter from a family member helping financially, landlord contact info (if applicable), letter of explanation for such problems as credit issues, and divorce-related documents (if applicable).


2. Can You Explain Which Types of Loans Are Best Suited For My Needs?

Watch out for loan officers who start peppering you with options before listening to your story. Different types of loans make sense for different types of borrowers.


Give the mortgage lender your financial picture and have the loan officer explain what options are available and how they would meet or not meet your needs.


There are tons of mortgage programs for buyers. Not every mortgage option is going to be suitable for your specific financial situation.


Should you opt for an FHA loan? Does a conventional mortgage make the most sense? Are you a veteran? Maybe a VA loan will be your best option.


Often, buyers ask if they should use an FHA loan or a conventional mortgage.


An exceptional mortgage broker will detail which loan programs make the most sense for you and why. Getting the best mortgage rate and terms for your needs will come down to asking the mortgage lender the right questions.


The mortgage officer should then have the ability to plug in the best package for you.

Buyers who rush into getting a loan can find themselves stuck with bad financing terms.


3. Do You Approve Loans In-House?

Do you approve your loans in-house? You will find various mortgage lenders, some with more capabilities than others.

The loan officer is the person you interact with, but others will be involved, like the mortgage underwriter, who will determine if you get the loan.

A company that approves loans in-house will be better equipped to adapt to potential hurdles in your mortgage.

For example, if there is a problem with your credit report, an in-house underwriter could discuss it with the loan officer and get it ironed out.

An out-of-house underwriter might deny the loan and move on with the following application.


4. How Long Will Mortgage Approval Take?

Finding out how long it will take to get your mortgage commitment is a crucial question to have an answer.

When you write an offer with your buyer’s agent, one of the more essential terms in the offer will be the mortgage financing contingency date.

It would be best if you had something that works with your chosen lender. There is no guarantee that a seller will grant a mortgage extension.

It is essential to be on the same page with your lender with critical contract dates.


5. What Kind of Down Payment Do I Need to Get a Loan?

Lenders still desire the standard 20% down payment, but that does not mean it is required to get a mortgage, far from it.

The need for a twenty percent down payment is a myth that’s traveled far and wide for years.

Some lenders will work with you even if you have down as little as 3%.

There are, in fact, three percent down conventional mortgages now available. And with specific specialized loan programs like FHA or VA loans, you can also get a loan with zero to 3.5% down.

The average down payment for first-time home buyers is around 6 percent, and for second-home buyers, around 11 percent.


Whatever the circumstances, you need to know the requirements for getting the loan before moving forward.

Keep in mind that it might be wise if you have twenty percent to put down. By having a twenty percent down payment, you will avoid paying private mortgage insurance, which can be costly.

Those who put less than twenty percent down will see how much of a burden the PMI payments can be. They will research how to stop paying private mortgage insurance as soon as possible.


6. Are There Any Special Financing Programs Available to Me?

Another intelligent question to ask a mortgage lender is whether any special mortgage programs could benefit your situation.

Approximately 2500 specialized programs around the country help buyers get a home. There are many options, most of which won’t apply to you. But maybe one or more of them do apply to you.

An outstanding lender will know what is necessary to guide you to programs that fit your situation. If the one you are talking to has no information or seems to have little interest in helping you in this area, find another lender.

Like any other business, there will be excellent and rotten eggs. If the mortgage officer is more concerned about “closing a deal,” you know, you’re in the wrong place.


7. Do You Charge an Origination Fee?

The origination fee is an expense charged by most lenders for setting up a loan. The lender you are dealing with may or may not have a fee. If they do, this expense may vary compared to the fee charged by other lenders.

You may be able to negotiate the origination fee. It can’t hurt to try!

Again it is vital to keep in mind the total cost of the loan. If one lender has an origination fee higher than another, that should not preclude you from choosing them. It is all about the total financial output on your part.


8. What Other Fees Do You Charge as a Lender?

Lender fees are pretty much unavoidable. They will attempt to make money where they can, above and beyond the interest you pay on your loan. But that does not mean every lender charges the same fees.

You should compare lender fees across several providers and weigh those fees along with other factors before choosing who to go with.

An important question to ask the lender upfront is how quickly they can put a loan estimate together for you.

Years ago, this used to be called the Good Faith Estimate.


The GFE was created to encourage buyers to shop and compare fees before deciding on a lender. The original purpose was to educate consumers on what services to bargain for to get the best interest rate, closing costs, and other terms.

The Good Faith Estimate would list all the costs associated with obtaining the mortgage.

Lenders are supposed to get the GFE to borrowers within three days of completing a loan application. The GFE is now called the loan estimate. The change was made under the current TRID guidelines.


9. What is The Interest Rate I Will Pay, and What Is The APR?

The interest rate you are charged on the loan is a significant factor to consider when choosing a lender.


You also need to pay attention to the APR or annual percentage rate. The APR adds the lender's fees and the interest rate, then divides the total by the mortgage term.

10. How Do You Calculate The Adjustments Made to Your Adjustable-Rate Mortgages?

An excellent question to ask a lender is whether to choose a fixed- or adjustable-rate mortgage.


If you don’t plan to stay in your home long, an adjustable-rate mortgage may be the best option.

For example, you may know you will be transferred within a few years.


You may or may not be interested in an adjustable-rate mortgage with an interest rate that changes periodically.

If you are interested in this kind of loan, you want to get clear answers on when and how the rate might change over the term of your loan.

Some things to consider include the following:

How regularly is the rate adjusted?

Do you provide notice when the rate will be changed, and if so, when?

Is there a cap on how much you can increase the rate?

Is there a limit on how much you can raise the interest rate in a year?

What if rates go down? Does my rate go down, too?

The answers to questions could determine whether you’re better off with a fixed-rate loan.


11. How Does Your Mortgage Rate Lock Policy Work?

When we are uncertain about interest rates, the rate lock can become a vital decision point in the loan. Many borrowers will want to have the comfort of locking their interest rate.

These are the questions you should be asking regarding rate locks:

Do you charge a fee to lock in my interest rate, and if so, what will it be?

How long will the rate lock be for?

Will there be a cost to extend the rate lock? How much will it be?

Will you give me the loan lock in writing?


12. Do You Charge a Penalty if I Repay Early?

Although some states have made it illegal to charge an early payment penalty, some states still allow it. You want to be aware of the consequences in case you try to pay the loan offer early.

Getting the home refinanced or going to another lender could lead to penalty fees with specific lenders. With the number of choices in lenders today, you’re probably better off skipping any mortgage companies that would charge a pre-payment penalty.


13. Can I Get a Pre-Approval For The Loan?

Difference between Pre-approved vs pre-qualifiedA pre-approval letter can make you more competitive when buying a home in a hot market.

Once a buyer sees that you have pre-approval. Pre-approval is not a guarantee but a big step in the process.

Keep in mind that pre-qualification is not the same as pre-approval. Pre-approval is harder to get but is much more reliable than pre-qualification.

With a mortgage pre-approval, a lender will verify your income, employment, and credit scores. With many lenders, a pre-qualification does none of these things.

The seller and listing agent will want a pre-approval letter if you purchase a home. A pre-qualification is worthless.


14. What Should I Avoid Doing to Preserve My Pre-Approval?

Changing your finances can cause a lender to say no, even if you have gotten pre-approval.

Ask the lender for a checklist of things not to do so that you can avoid losing your loan.

One of the most common ways buyers lose their loan approval is by purchasing a car while buying a house.

An excellent mortgage broker will go over everything a borrower should not do so the loan goes through without a hitch.


15. How Likely Do You Think I am to Get The Loan I Want?

The loan officer is one of the best-qualified people to ask about the likelihood of getting the loan you are after. They can give you informed advice on what to do to get the loan and should be able to look closely at your circumstances to tell you whether or not you are likely to be approved.

If you have a steady job, good credit, and an income that doesn’t fluctuate, a lender should be able to give you confidence getting the mortgage won’t be a problem.

Asking a mortgage lender is essential because if you are told no, you must make changes before buying a home.


16. What is The Minimum Credit Score With The Mortgage Programs You Offer?

Knowing there are minimum credit scores to buy a house is essential. Some lenders will have mortgage programs that others don’t offer.

You could be a marginal buyer when you don’t have the best credit score. Getting loan approval will be more challenging.

Asking a mortgage lender this question upfront will be essential.


17. What Will My Mortgage Payment Be?

This a simple question but one you’ll probably be very interested in finding out for financial planning purposes. Your loan officer or mortgage broker can provide your payment schedule.


18. What Are My Closing Costs?

Most buyers want to know what monies they need to bring to closing. Closing costs are highly variable. This will be a crucial question for your mortgage lender. You will more than likely need to get a certified check.

There are many costs when buying a home, but a lender should break out their specific fees.


19. How Does The Loan Estimate Work?

If you don’t know, loan estimates break down the costs of getting a mortgage. Mortgage lenders must provide buyers with a loan estimate within three business days of your loan application.

Lenders must send you a new loan estimate when anything changes with the estimate. Your mortgage costs should only vary minimally from your initial loan estimate.

It is possible that third-party fees for things such as a property survey, title insurance, or real estate appraisal can vary by as much as ten percent.

Always ask your mortgage lender questions when it comes to any fees.


20. What Happens if The Real Estate Appraisal Comes in Low?

Occasionally, home appraisals come in lower than the agreed-upon sale price. When this happens, there is an appraisal gap.

It is good to know how your lender will treat the situation. For example, if the gap is significant, you will likely need to increase your down payment or renegotiate with the seller.

If you have more than twenty percent down, the lender may feel they have ample equity in the property. Asking this question before committing would be wise.


21. Do You Plan to Sell My Loan?

Your chosen mortgage lender may no longer service the loan after closing. If this is important to you, find out upfront. When you run into a tough financial spot, the servicer is who you will speak with.


22. What Will I Need to Bring to Closing?

Any loan officer worth their salt will prepare a buyer before closing. Understanding what is required to bring to the closing table is essential.


Most lenders have similar requirements for borrowers. You can use this house-closing checklist as a reference. It is likely to contain all the requirements for most lenders.


23. Do You Have Any References?

This last question to ask a lender or mortgage broker is essential. Like any other company you are hiring, doing your due diligence is vital. The loan officer you are using should be able to provide you with some satisfied clients.


While you may think the loan terms are the most crucial aspect, the service you receive should never be discounted.


Ask any real estate agent, and they are bound to be able to convey mortgage broker horror stories.
Posted in Buying
April 20, 2026

How Your Backyard Can Increase The Value Of Your Home

A well-designed backyard can increase your home's value by up to 15-20%. In 2026, outdoor living spaces have become the most desired feature for homebuyers, often outranking interior upgrades because they expand usable living area without the cost of a full home addition.


Decks & Patios: These features create "outdoor rooms" for dining and relaxing. A new wood deck typically recoups about 83% of its cost, while patios see an average ROI of 60% to 70%.

Outdoor Kitchens: Increasingly popular as "culinary suites," functional outdoor kitchens with built-in grills and durable countertops can recoup 55% to 200% of their cost, depending on the market.

Mature Trees: A healthy, mature tree can increase property value by $1,000 to $10,000 by providing shade, privacy, and aesthetic appeal.

Fire Features: Permanent fire pits or outdoor fireplaces serve as natural gathering spots and can offer a 50-70% ROI. 


Key Value Drivers for 2026

Expanded Living Space: Buyers perceive decks, patios, and pergolas as "bonus square footage" for hosting and relaxing.

Privacy: Enclosed yards with high-quality fencing (wood or vinyl) or "green screens" like hedges are top priorities for buyers with children or pets.

Sustainability: Eco-friendly features like native, drought-resistant plants (xeriscaping), solar-powered lighting, and smart irrigation systems are highly attractive to modern, eco-conscious buyers and lower future maintenance costs.

Nighttime Ambiance: Professional outdoor lighting enhances safety and expands the yard's usability after dark, adding roughly $2,500 in perceived value

Features to Avoid

Certain upgrades may actually detract from value or fail to recoup costs: 

Over-Personalization: Highly specific features like built-in trampolines, elaborate themed gardens, or specialized sports courts can limit buyer interest.

High-Maintenance Items: While pools can be a major selling point in warmer climates, they may only recoup about 56% of costs due to perceived maintenance burdens.

Excessive Concrete: Large, plain concrete slabs can create "heat islands" and drainage issues, potentially lowering value by up to 12% compared to yards that mix hardscaping with greenery

Posted in Selling
April 20, 2026

Why You Need a Real Estate Agent

Every year, a small portion of homes are put up for sale by owner (FSBO). But according to the National Association of REALTORS® (NAR), selling without a realtor makes the process more difficult. Here’s a few reasons why hiring an agent can save you time, energy, and reduce stress.

Industry know-how

You probably don’t have a lot of experience with the ins and outs of real estate. The industry can be tricky to navigate, but an agent has the education and experience to back up his or her decisions.


Negotiation skills

If you don’t fancy yourself an expert negotiator, that’s where a real estate agent comes in. REALTORS® have mastered the art of negotiating and can ensure your home sells for a fair price.


Confusing paperwork? Handled.

Instead of spending hours on the internet to find out what escrow means, your agent can explain everything to you in basic terms and handle the often-difficult process of navigating a real estate transaction.


Working for you

Agents are required to have your best interest in mind, which can be a breath of fresh air during a particularly stressful process. It’s beneficial to have an expert opinion to back you up and marketing expertise to make sure your home is seen by the right people.


A neighborhood authority

Whether you’re moving down the street or four states away, choose an agent with extensive knowledge of the neighborhood you’re interested in. The agent will know the average price of homes in the area, plus extra information you might not be able to find in an internet search.


I’ve got my keys and my local market data ready. Whether you're looking to list your current place for top dollar or you're ready to find that "diamond in the rough" home, I'm here to guide you through the process.

Here is how I can help you as your REALTOR®:

Expert Representation

Strategic Listing: If you're selling, I'll handle everything from pricing analysis and professional staging consultations to high-quality photography to ensure your home stands out.

Buyer Advocacy: For buyers, I’ll set up tailored searches, investigate flood zones and permits, and help you navigate the often-emotional "rocky" moments of the purchase.

Master Negotiation: I handle the tough conversations regarding price, repairs, and closing costs, keeping your best interests at the forefront.

The REALTOR® Difference: Unlike a standard real estate agent, I am a member of the National Association of REALTORS® (NAR), meaning I adhere to a strict Code of Ethics and have access to exclusive market data and the Multiple Listing Service (MLS).

Posted in Buying, Selling